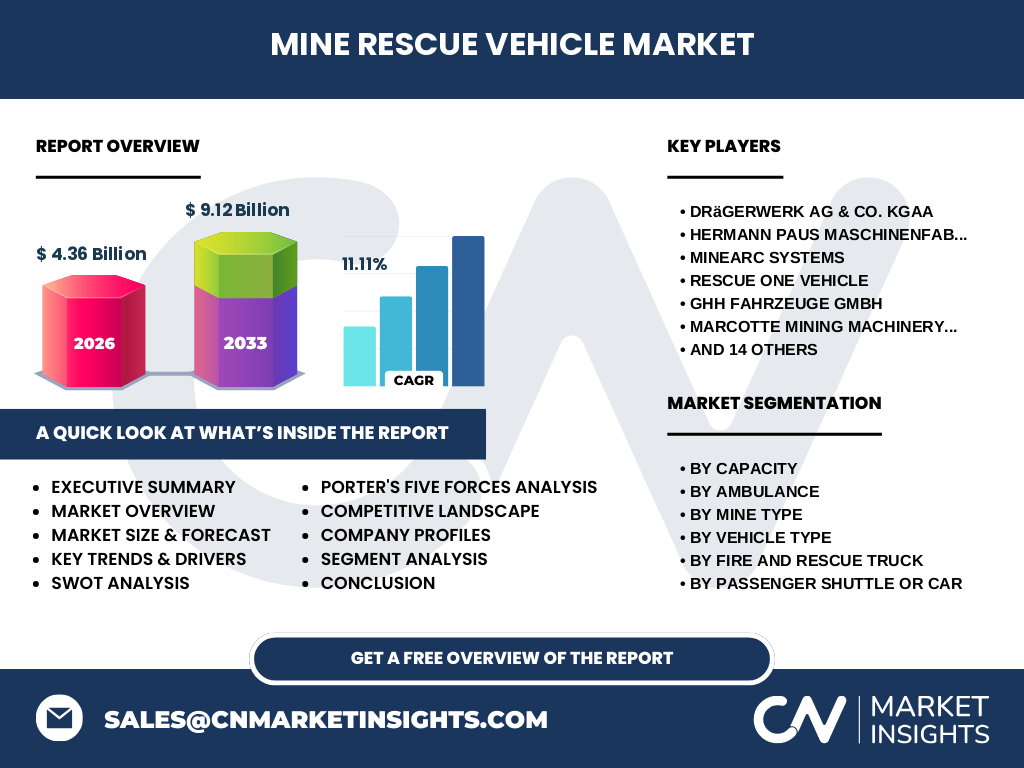
Overview of the Mine Rescue Vehicle Market scope and industry significance
The Mine Rescue Vehicle Market represents a mission-critical segment of the global mining infrastructure, focused on specialized machinery designed for rapid subterranean emergency response. Valued at 4.36 Billion in 2026, these vehicles integrate advanced life-support, fire suppression, and extraction technologies. Their significance lies in mitigating life-safety risks within high-hazard coal and mineral extraction environments, mandated by stringent international safety protocols enforced by bodies like MSHA and OSHA.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by heightened regulatory pressure and the imperative for mining firms to lower Lost Time Injury Frequency Rates (LTIFR). While the sector faces logistical hurdles—specifically the physical constraints of narrow-vein underground tunnels—it is balanced by significant opportunities in automated evacuation. Our analysis indicates that companies like MacLean Engineering and Epiroc AB are pivotal, leveraging advanced navigation systems to bypass typical navigation constraints in complex mine geographies.
Emerging Trends in Mine Rescue Vehicle Technology
A definitive shift toward electrification and remote-controlled operation characterizes current industry trends. As mining operations venture deeper into hazardous strata, the adoption of Hazardous Material Response Trucks and automated Evacuation Shuttle Vehicles has surged. This transition not only enhances rescue speed but also reduces human exposure during critical fire and rescue operations, positioning manufacturers like MineARC Systems as leaders in providing high-reliability, technology-driven subterranean solutions.
COVID-19 Impact and Recovery Trajectory
The pandemic forced a temporary contraction due to supply chain bottlenecks involving critical raw materials like specialized steel and electronic sensor components. However, the Mine Rescue Vehicle Market exhibited a resilient recovery. Increased focus on site safety and isolated emergency protocols acted as a catalyst for capital expenditure. By 2026, the market normalized, creating a robust base for the forecasted 11.11% CAGR through 2033.
Competitive Benchmarking and Market Concentration
The market landscape is highly concentrated, with dominant incumbents such as Sandvik AB, Caterpillar Inc., and Normet Group Oy holding substantial shares. These firms leverage extensive global distribution networks and deep R&D budgets to outperform localized competitors. Strategic dynamics involve frequent cross-sector partnerships, particularly where Becker Mining Systems AG integrates communication technologies into emergency medical transport vehicles to provide real-time vital sign monitoring during transit.
Executive Summary: The Future of Subterranean Safety
The Mine Rescue Vehicle Market is poised for significant expansion, scaling from 4.36 Billion in 2026 to 9.12 Billion by 2033. This growth is underpinned by an 11.11% CAGR. Strategic investment in Heavy Duty Mine Rescue Vehicles and specialized Hazardous Material Response Trucks is essential for operators facing increasingly complex geological and regulatory challenges. Safety-first mandates are now the primary driver of fleet renewal cycles.
Projected Market Valuation for 2027-2033
Based on our quantitative modeling, the market valuation is set to reach 9.12 Billion by the end of 2033. This forecast reflects a 11.11% CAGR, driven by the replacement of aging fleets and the integration of Industry 4.0 standards. We anticipate peak growth periods between 2029 and 2031, as mining firms in Australia, South America, and Africa accelerate their digital safety infrastructure mandates.
Breakdown of Market Segmentation
Our analysis classifies the market into key segments: Capacity (Light/Medium vs. Heavy Duty), Ambulance type (Mine Ambulance vs. Emergency Transport), and Mine type (Underground vs. Coal). Each segment serves specific tactical needs; for instance, Personnel Transport Vehicles are essential for daily logistics, whereas Firefighting Trucks provide the high-pressure response capabilities required for deep-vein coal mining operations, where risk profiles are significantly higher than in open-pit mining.
Geographic Performance and Regional Distribution
Regional performance is dictated by the density of underground extraction sites. North America and Europe lead in terms of technological adoption, while the Asia-Pacific region dominates in volume due to massive coal mining operations in China and India. The presence of major ports in regions like Western Australia facilitates the rapid deployment of equipment from manufacturers like GHH Fahrzeuge GmbH, ensuring localized support for geographically remote and harsh mining sites.
In-depth Regional Review: Strategic Hotspots
In North America, demand is heavily influenced by strict MSHA safety requirements, driving high-end sales of specialized Rescue and Extrication Vehicles. Conversely, in the CIS and Asia-Pacific markets, the focus remains on high-capacity, durable equipment provided by companies like China Coal Group and Joy Global Inc., which prioritize robustness and ease of maintenance in environments where specialized, on-site technical support may be limited.
Company Profiles and Strategic Positioning
Leading entities like Drägerwerk AG & Co. KGaA focus on high-fidelity life-support integration, positioning themselves as premium, safety-critical suppliers. Hermann Paus Maschinenfabrik GmbH and Getman Corporation differentiate through modular engineering, allowing for custom vehicle configurations. These strategic positions enable them to capture share in segments where precision is non-negotiable, while larger conglomerates like Caterpillar Inc. utilize massive manufacturing scales to dominate the general underground personnel transport sub-segment.
Porter's Five Forces Assessment
The Mine Rescue Vehicle Market faces intense competitive rivalry due to a concentrated player base. Barriers to entry are notably high, requiring deep engineering expertise and strict compliance certifications. Buyer power is moderate, influenced by the specialized, non-substitutable nature of the equipment. Supplier power over raw materials—specifically high-tensile steel and specialized hydraulic parts—remains a critical bottleneck that keeps manufacturing costs volatile and high for all participants.
SWOT Analysis: Navigating Industry Risks
The market's strength lies in rigid regulatory mandates that ensure consistent demand. Weaknesses include the high cost of R&D and specialized manufacturing. Opportunities abound in the transition to autonomous emergency response, while threats include geopolitical instability in key mining regions and potential supply chain disruptions for semiconductor components, which are increasingly vital for the navigation and monitoring systems within modern rescue fleets.
Value Chain Analysis: From Raw Materials to End-Users
The value chain commences with raw material procurement (steel, polymers, electronic components) and flows into specialized manufacturing by players like Arva Industries Inc. and BAS Mining Trucks. These firms add value through intense R&D. Distribution involves direct sales or certified dealership networks to mining conglomerates, where the final value is delivered through preventative maintenance contracts and long-term service agreements that ensure the constant operational readiness of the vehicles.
Investment Insights and High-Potential Areas
We identify autonomous vehicle development and remote vital-sign monitoring systems as high-potential investment areas. Investors should prioritize firms that are transitioning toward Battery Electric Vehicle (BEV) platforms, as these offer lower emissions and reduced ventilation requirements in underground tunnels. The data suggests that companies integrating predictive maintenance software into their existing fleet offerings are likely to capture higher margins as miners demand increased equipment availability and uptime.
Conclusion and Key Takeaways
The Mine Rescue Vehicle Market is a stable, high-growth sector essential to the global commodity supply chain. Reaching 9.12 Billion by 2033, the market reward for technical innovation is significant. Stakeholders should focus on the Heavy Duty and Hazardous Material Response segments, where regulatory requirements and the need for operator safety remain the primary drivers of long-term capital investment and strategic partnership formation across the mining sector.
Research Methodology: Triangulation and Validation
Our baseline estimates are derived from a triangulation approach. We combine proprietary trade registry data with quarterly financial reports from public manufacturers like Sandvik and Epiroc. This is validated by primary stakeholder interviews with mine safety officers and regional regulators. We correlate these findings against macroeconomic indicators such as global mineral consumption rates and mining industry capital expenditure cycles to ensure high-confidence projections.
Scope and Parameters of the Report
This report covers the Mine Rescue Vehicle Market globally, specifically focusing on equipment designed for underground, tunnel, and coal mining environments. Our scope excludes light-duty passenger vehicles not certified for mine-specific safety/rescue operations. Limitations include variations in regional data reporting, which we mitigate through rigorous standardized cross-referencing of local government mandates and trade statistics provided by major mining associations and industrial regulatory bodies.
Recent Developments and Market Signals
Recent announcements indicate a strong trend toward Strategic Partnerships. For example, Marcotte Mining Machinery Services Inc. has increased focus on localized refurbishments, while players like Kovatch Mobile Equipment Corp (KME) have announced new fire suppression technology launches tailored for deep-shaft environments. These moves signal a competitive pivot toward specialized equipment performance and longer service life, directly responding to the demands of modern, deep-level mining operators globally.